Need money for a medical expense, a family emergency, a wedding, education, or simply to manage a tough month? You are not alone. Every day, people search for how to get a personal loan in Pakistan because they need a practical solution, not confusing financial jargon.
The problem is that most people do not just have one option. Some qualify for a personal loan from a bank in Pakistan. Some look for interest-free personal loan options.
Some search for loan apps in Pakistan, hoping for a quick answer. And many end up borrowing from family, friends, or private contacts without any proper written agreement. That is where confusion begins, and where problems often follow.
This guide explains your real loan options, what to check before borrowing, and how to stay protected if the loan is private. While banks and certain nonprofit lenders offer formal lending routes, Amana helps make private lending safer through contracts, verification, and recovery support.
Main Ways to Get a Personal Loan in Pakistan
If you are wondering how to get a loan in Pakistan, there are usually four routes people explore.
The first is a bank personal loan, which works best for people who can show stable income, supporting documentation, and the ability to repay. The second is an interest-free loan option, usually available through specific institutions and not always instant. The third is through online loan apps or digital lending platforms, which may feel faster but should be reviewed carefully.
The fourth is private lending, where the money comes from a person rather than a bank. That last option is very common in Pakistan, but it is also where the biggest misunderstandings happen when there is no proper agreement in place.
Personal Loan from a Bank
For many people, this is the first option that comes to mind. A bank loan usually offers a structured repayment plan, formal terms, and a clear installment schedule.
Banks like HBL market personal loan products based on eligibility, income, and repayment capacity. They also make it clear that applying does not automatically mean approval.
Interest-Free Personal Loan Options
If you are specifically searching for how to get an interest-free personal loan in Pakistan, you are probably looking for an option that avoids markup. These loans do exist, but they are typically offered through specific social finance or nonprofit models.
They also follow their own process. Akhuwat, for example, states that applicants must have a valid CNIC, be within the age range of 18 to 62, and apply through its branch-based process rather than online.
Online Loan Apps and Digital Lending Platforms
Many people now search for online loans in Pakistan, loan apps in Pakistan, or easy loans because they want a quicker route. That makes sense. But faster does not always mean safer.
Before using any digital lender, it is important to understand the fees, repayment schedule, privacy permissions, and the company behind the app.
Private Lending Options in Pakistan
This is the route many people actually use, even if they did not originally plan to. The money may come from a relative, a friend, or a business contact willing to lend on trust.The flexibility can be helpful, but without proper documentation, both sides are exposed. Amana is built around this exact gap by offering legally structured contracts, digital records, verification, and support for private lending arrangements.
If your loan is being arranged privately, make it clear, documented, and safer with Amana from day one.
How to Get a Personal Loan from a Bank in Pakistan
If your goal is to get a personal loan from a bank in Pakistan, the process is usually straightforward on paper. The real challenge is making sure your profile actually matches the lender’s criteria.
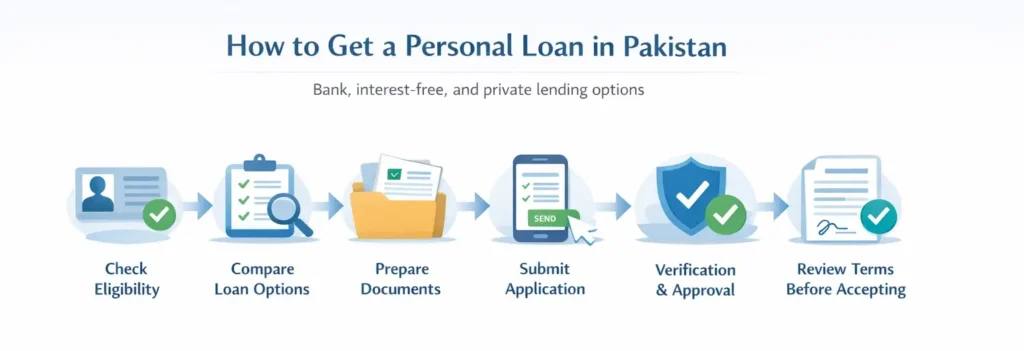
Check Your Eligibility
Before applying anywhere, check whether you meet the bank’s basic requirements. HBL personal loan eligibility criteria usually depend on things like age, monthly income, employment type, and repayment capacity.
HBL’s current personal loan pages, for example, state that a financial profile determines the amount. The application form also says submission does not guarantee approval.
Compare Banks and Loan Offers
Do not apply blindly just because one option looks quick. Compare the installment amount, loan tenure, processing fee, and full repayment cost.
Some people focus only on the monthly amount and ignore what they will actually repay over time. That can be a costly mistake.
Prepare the Required Documents
In most cases, you should be ready with your CNIC, proof of income, salary information or business details, and bank statements. HBL’s application and financing pages make clear that income and profile details are central to the process.
Related HBL documentation pages also show that proof of income and identity documents are commonly required.
Submit the Loan Application
Once your documents are ready, you can apply through the bank’s branch, website, or app, depending on the lender. Fill in your details carefully.
A small mismatch in income or personal information can delay the process.
Complete Verification and Approval
After submission, the lender usually checks your documents, profile, and repayment ability. Some banks offer digital application convenience, but approval still depends on internal assessment.
HBL explicitly says application submission does not guarantee approval.
Review the Terms Before Accepting
Before you accept any personal loan, read everything. Processing fees, charges, tenure, and repayment terms matter just as much as the approved amount.
A loan that feels easy today can become stressful later if the terms were not properly understood.
Types of Personal Loans in Pakistan
When people search for types of personal loans in Pakistan, they are usually trying to figure out what kind of borrowing actually fits their situation.
Unsecured Personal Loans
These are the most common types of personal loans. They usually do not require collateral. Approval depends more on your profile, income, and repayment ability.
Secured Personal Loans
These involve some form of backing, such as an asset or structured security. They are less common in everyday personal borrowing but still exist in certain financing arrangements.
Bank Personal Loans
These are formal loans offered by banks and financial institutions. They are usually repaid in installments over a fixed tenure and come with documented terms.
Interest-Free Personal Loans
These are offered through special social finance or nonprofit models rather than standard commercial lending. Akhuwat publicly lists multiple loan products and an interest-free loan process.
This shows that this route exists but operates under specific requirements.
Online Personal Loans
These are loans applied for through apps, websites, or digital channels. The convenience can be appealing, but the terms should always be checked carefully.
Purpose-Based Personal Loans
Many people do not search by loan category. They search based on need — wedding loan, education support, emergency funds, travel, home improvement, or personal cash flow support.
That is why a strong article should answer both the financing question and the decision-making question.
Eligibility Criteria for Personal Loans in Pakistan
If you are asking how I can get a personal loan in Pakistan, eligibility is where the answer usually starts.
Most lenders look at your age, income, job or business stability, current liabilities, and ability to repay. Personal loan approval usually depends on your overall financial profile and the lender’s eligibility criteria.
Requirements can also vary depending on whether you are salaried, self-employed, or a pensioner. The better your documents and repayment profile, the stronger your chances.
Documents Required to Apply for a Personal Loan in Pakistan
While requirements can differ from lender to lender, borrowers in Pakistan are commonly asked for:
- valid CNIC
- proof of income
- salary slip or salary certificate
- bank statement
- employment or business proof
- contact information
- address details
Official lender pages and supporting banking documents show that identity and income proof are routine parts of personal finance applications.
Which Bank Gives Personal Loans Easily in Pakistan?
This is one of the most searched questions, but the honest answer is: there is no single bank that gives loans easily to everyone.
A bank that suits one borrower may not suit another. One person may qualify because they have salary credits, another because they have an existing banking relationship, and another may not qualify at all.
Even most banks’ personal loan pages make it clear that loan size and approval depend on lender criteria. Submitting an application is not the same as getting approved.
So instead of asking which bank is easiest, ask which one fits your financial reality best.
Can You Get an Interest-Free Personal Loan in Pakistan?
Yes, but with the right expectations.
An interest-free personal loan in Pakistan is possible through certain institutions, but it is not usually an instant online cash product. Akhuwat’s public process states that applicants must meet its criteria, have a valid CNIC, and apply through a branch-based route.
It also states that Akhuwat does not offer loans online.
Borrowing from Friends or Family
This is one of the most common real-life options. It can be more flexible and more humane than dealing with a bank.
But flexibility without clarity can later turn into tension.
Private Lending with Proper Documentation
This is where private borrowing becomes safer. If the arrangement is clear, recorded, and mutually acknowledged, both sides know where they stand.
Amana’s platform is built for this exact situation, offering structured contracts, repayment terms, acknowledgement trails, and verification support.
Why Informal Lending Can Be Risky
Informal lending often starts with trust and ends with confusion. Who agreed to what? When was repayment due?
Was there a grace period? Were installments discussed? Without written proof, these simple questions become real disputes.
Borrowing from someone you know? Protect the relationship by documenting the loan properly through Amana.
Are Loan Apps in Pakistan Safe?
The safer answer is: some may be, some may not be, and you should never assume.
Risks of Using Unverified Loan Apps
Unclear charges, vague repayment terms, poor customer support, and confusing permissions are all warning signs. If a platform is pushing urgency but avoiding transparency, that should concern you.
How to Check If a Loan App Is Reliable
Look for a clear company identity, readable terms, a repayment schedule, visible contact details, and a credible support channel. If those basics are missing, move carefully.
Bank Loan vs Interest-Free Loan vs Private Loan in Pakistan
| Feature | Bank Loan | Interest-Free Loan | Private Loan |
| Source of funds | Bank or formal financial institution | Nonprofit, social finance, or selected private arrangements | Family, friends, investors, or private contacts |
| Approval basis | Eligibility, income, documents, and repayment capacity | Specific criteria set by the provider | Mutual agreement between borrower and lender |
| Documentation | Usually formal and structured | Usually structured, depending on the provider | Often informal unless properly documented |
| Repayment terms | Fixed installments and defined tenure | Based on provider terms | Flexible and mutually agreed |
| Cost structure | Usually includes markup, profit, or charges | Usually, no interest, depending on the model | Can be interest-free or mutually agreed |
| Speed | Moderate, depends on review and approval | May take time depending on the process | Often faster if both parties agree quickly |
| Flexibility | Lower, based on lender policy | Limited by provider rules | Higher, because terms can be customized |
| Risk level | Lower when terms are understood clearly | Moderate, depends on provider and terms | Higher if there is no written agreement |
| Best suited for | Borrowers who meet formal eligibility criteria | People seeking interest-free options | People who need flexible or relationship-based borrowing |
| Main challenge | Strict eligibility and approval requirements | Limited availability and specific conditions | Lack of structure, proof, and legal clarity |
| How Amana fits in | Not the primary use case | May support private documented arrangements | Helps formalize private lending with contracts, verification, and clarity |
What to Check Before Taking a Personal Loan in Pakistan
Before accepting any loan, check:
- the interest or profit rate
- the total repayment amount
- the repayment period
- any fees or penalties
- the exact terms and conditions
Do not judge a loan only by whether you can get it. Judge it by whether you can repay it comfortably and understand it fully.
Common Reasons Personal Loan Applications Get Rejected
Personal loan applications are often rejected because of low income, incomplete documents, weak repayment capacity, unstable income history, or a mismatch between the borrower’s profile and the lender’s criteria.
Since lenders set their own rules, rejection from one lender does not automatically mean rejection everywhere. Approval usually depends on repayment ability rather than simply submitting an application.
Common Mistakes to Avoid When Applying for a Personal Loan
- Borrowing more than you actually need
- Focusing only on speed instead of loan terms
- Ignoring the full repayment cost
- Overlooking fees, penalties, or hidden charges
- Applying without checking eligibility first
- Taking money privately without proper documentation
- Assuming trust alone is enough in private lending arrangements
What to Do If You Do Not Qualify for a Bank Loan
Not qualifying for a bank loan does not mean you have no options. It just means you need to choose more carefully.
Consider Alternative Loan Options
You may still be able to explore interest-free models, other formal lenders, or a private arrangement that better matches your situation.
Avoid Undocumented Borrowing
This is where many people go wrong. They take money from someone they know and assume everything will stay simple.
But when there is no written agreement, things can get complicated quickly.
Choose a Safer Private Lending Route
If the loan is private, make it professional. Amana is designed to help borrowers and lenders in Pakistan create clear agreements, verify counterparties, and reduce the risk of future disputes through proper documentation and support.
If the bank route is closed, do not switch to risky informal borrowing. Use Amana to formalize a safer private lending arrangement.
How Amana Helps Make Private Lending Safer in Pakistan
This is where the conversation becomes real.
Not everyone gets a bank loan. Not everyone wants one either. In Pakistan, much borrowing occurs informally — among relatives, friends, investors, and personal contacts.
That is exactly where Amana steps in.
Digital Loan Documentation
Amana says users can create legally structured contracts in minutes, with clear repayment schedules, due dates, late-payment terms, and witness or acknowledgment workflows, all within lawful boundaries, along with a secure digital trail of who accepted what and when.
Identity and Background Verification
The platform also highlights verification and risk checks, giving lenders and borrowers greater confidence before agreeing.
Clear Terms for Both Parties
This matters more than people think. Clear terms do not just protect money. They protect relationships.
Better Protection Against Disputes
Amana also presents recovery support as part of its broader platform. This helps users move from vague verbal arrangements to something more structured and defensible if issues arise later.
Want a safer way to borrow or lend privately in Pakistan? Start with Amana and turn an informal arrangement into a clear, documented agreement.
Frequently Asked Questions
Yes, a written agreement is strongly recommended. It helps both sides clearly record the loan amount, repayment terms, due dates, and other conditions, reducing the chances of confusion or disputes later.
There is no one-size-fits-all answer. Banks evaluate borrowers differently, and approval depends on your profile rather than the advertisement alone.
The safest approach is to make sure the loan terms are clearly documented, both parties are verified, and there is a reliable record of what was agreed. This is especially important when borrowing from friends, relatives, or private contacts.
Some may be, but you should always verify the provider, the terms, and the repayment conditions before proceeding.
Some lenders and digital platforms support online loan applications in Pakistan, but approval still depends on your profile, eligibility, and required documents. Applying online may be more convenient, but it does not guarantee approval.
Final Thoughts on Getting a Personal Loan in Pakistan
A personal loan in Pakistan is not just about getting money. It is about choosing a path that is realistic, understandable, and safe for your situation. For some people, a bank loan will be the right answer. For others, an interest-free option may be a better fit.
And for many in Pakistan, the real answer is private lending — but private lending done properly, with clarity and proof. That is the real opportunity for Amana. It is not just helping people borrow or lend. It is helping them do it with more confidence, less confusion, and far less risk.
If your personal loan is being arranged privately, use Amana to document it clearly, verify the other party, and protect both sides before money changes hands.
